Too many organizations treat financial archives like a junk drawer: everything tossed in but hard to find when it matters. A tidy archive speeds reporting, reduces audit stress, and limits accidental exposure. The trick is making records easy to retrieve while respecting retention rules and access limits. This piece outlines practical steps that prioritize searchability, minimal friction, and straightforward controls.
Organize by business need, not file type
Folders named by document format or software create busy paths that confuse teams during tight deadlines. Instead, group files by business events—quarterly close, payroll run, tax filing—so people find every relevant item in one place. Consistent naming patterns that include date and event cut ambiguity and reduce duplicate searches. When teams expect the same structure across periods, search habits become predictable and fast.
Start small with a handful of top-level categories tied to reporting cycles. Enforce the structure with clear examples so new files land where others expect them to be.
Capture searchable metadata up front
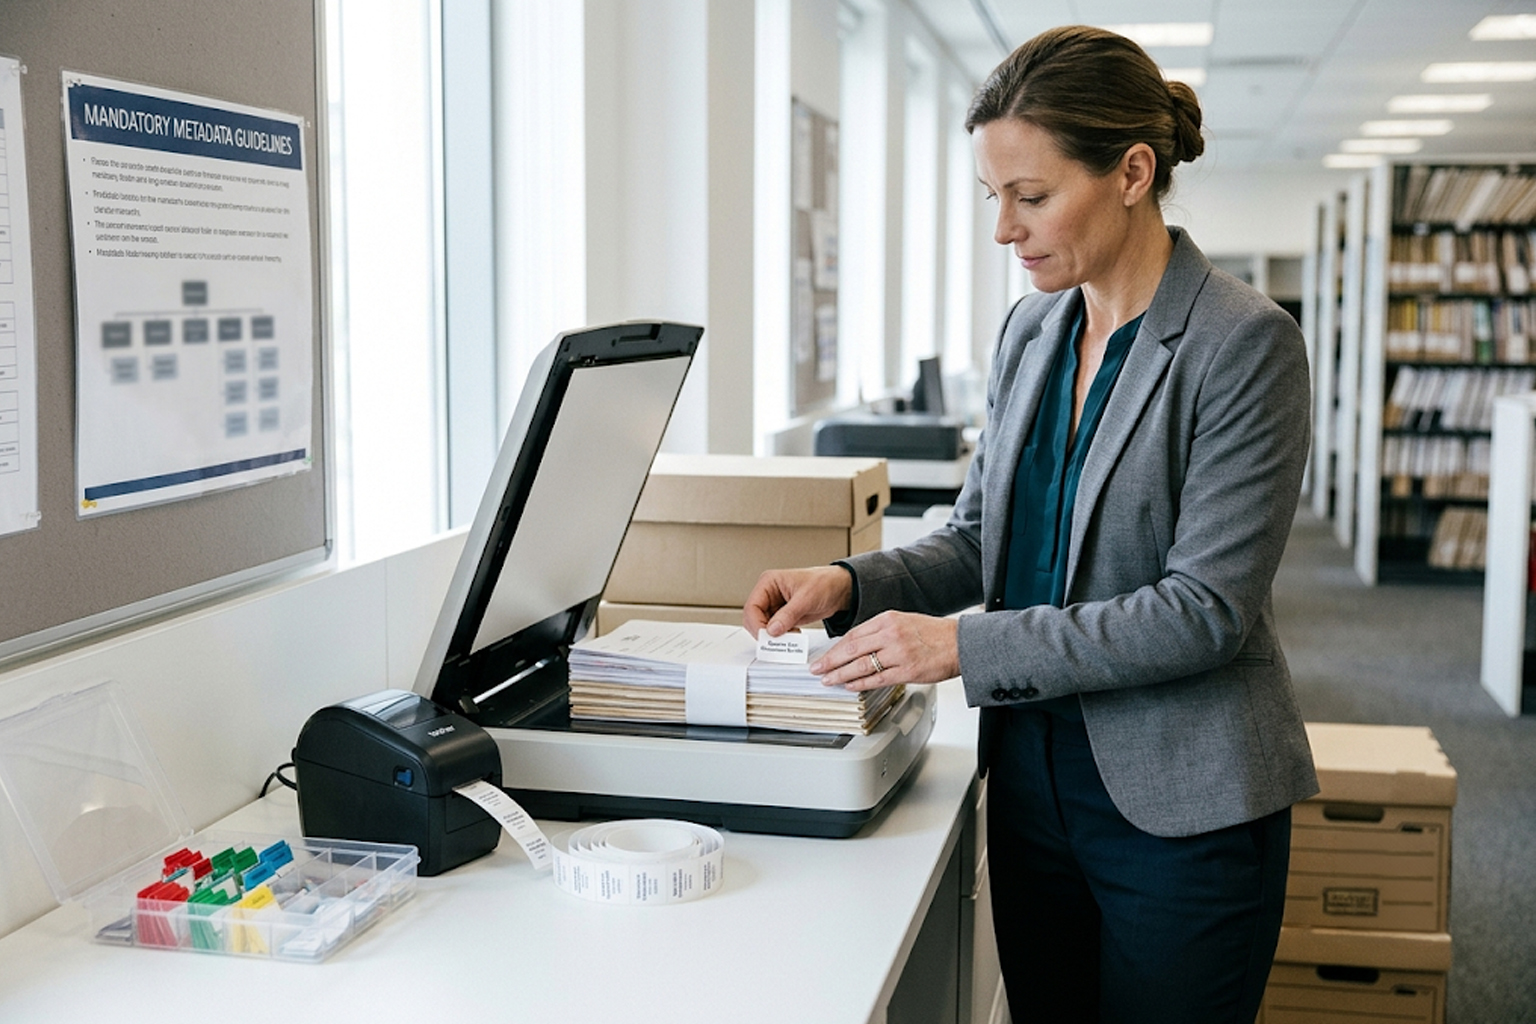
Relying only on filenames leaves helpful details buried in file contents. Capture key metadata—period, entity, document type, preparer—at upload so filters return precise results. Simple metadata fields outperform sprawling tag systems because they remain consistent and machine-readable. When metadata is mandatory for uploads, downstream work like consolidation and audit preparation becomes less manual.
Make the most useful fields required and keep optional ones minimal. Regularly review which metadata drives searches and trim anything that adds complexity without value.
Keep access and retention rules simple
Complex permission matrices and bespoke retention schedules create administrative overhead and mistakes. Define a small set of access roles aligned with job functions and attach them to folders or tags rather than individual files. Use clear, age-based retention policies tied to business events to reduce guesswork about what should be archived or destroyed. Simpler rules are easier to enforce and easier to explain during audits.
Automate routine enforcement where possible, but schedule periodic reviews so exceptions are handled deliberately. A few well-documented exceptions are preferable to dozens of undocumented workarounds.
Conclusion
Practical archives combine predictable structure, required metadata, and straightforward controls to make records fast to find. Start with small, enforceable changes that directly reduce search time and audit effort. Over time, those habits produce an archive that both supports reporting and limits risk.
