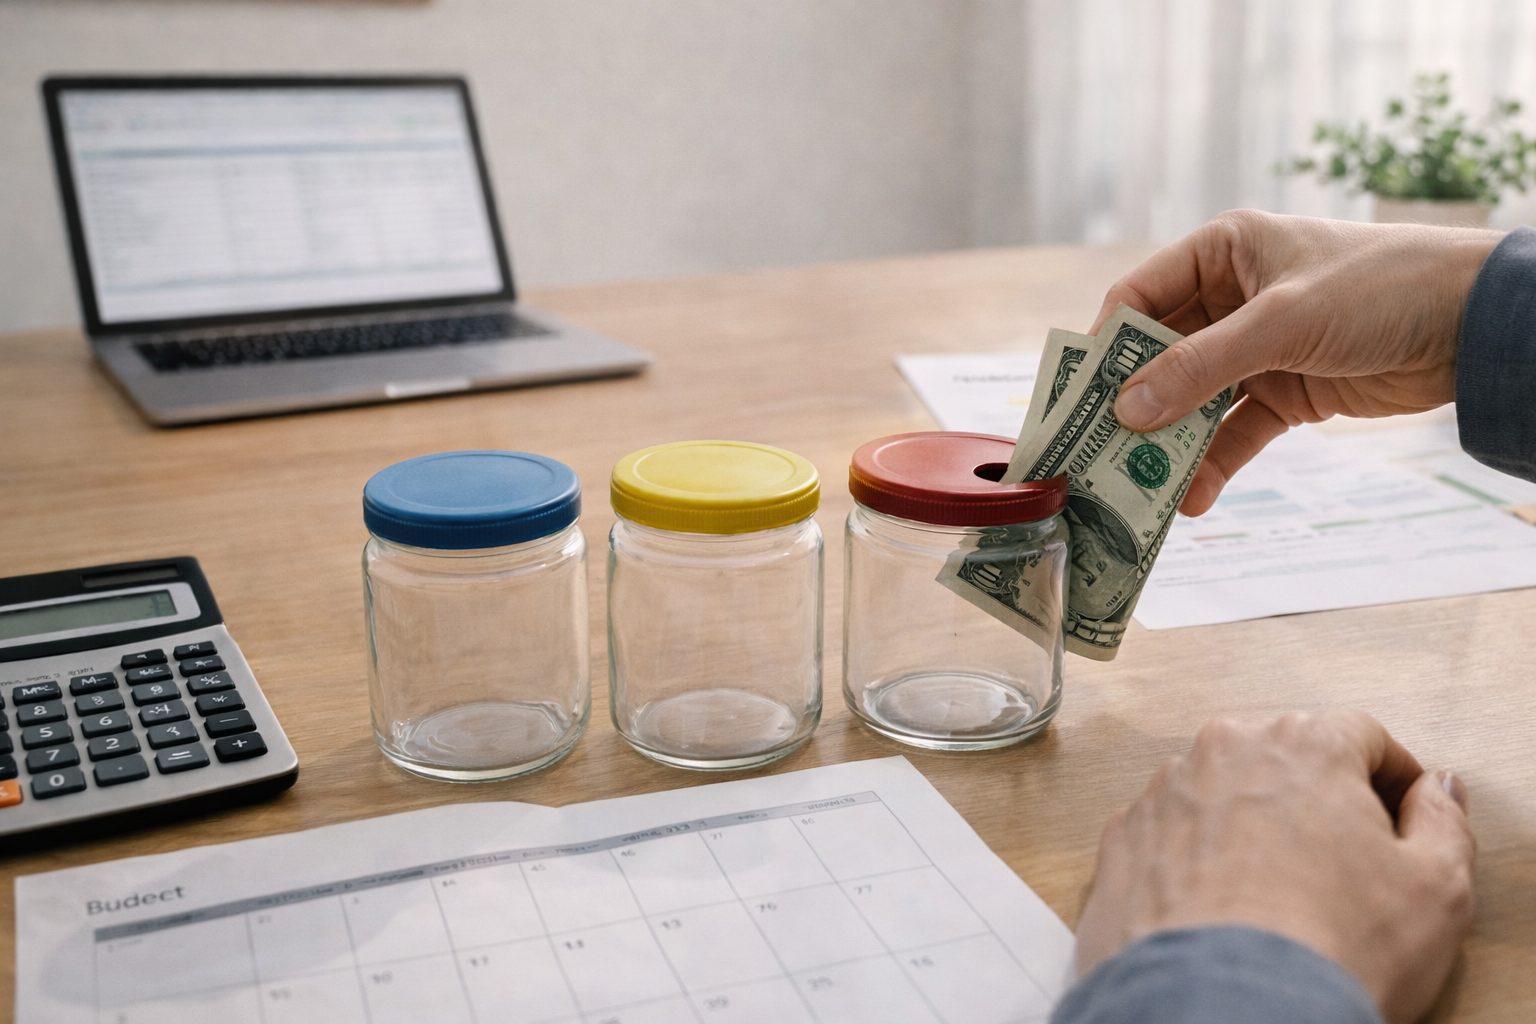
Having a dedicated emergency fund is the foundation of practical financial security.
It reduces the need to borrow under pressure and preserves long-term goals when unexpected costs arise.
Building and maintaining that fund requires intentional habits and a strategy that balances liquidity with modest growth.
This article outlines actionable steps to protect those savings while improving their purchasing power.
Why an Emergency Fund Matters
An emergency fund provides a buffer that keeps short-term shocks from derailing progress toward larger financial goals. It offers immediate access to cash for job loss, urgent repairs, or medical expenses without forcing high-interest borrowing. The psychological benefit of knowing a cushion exists can also reduce stress and improve decision making during crises. Prioritizing this fund changes how you respond to volatility and helps maintain overall financial stability.
Start by defining a clear target and timeline for your reserve based on living expenses and risk tolerance. Treat contributions as a recurring obligation so the fund grows predictably over time.
Practical Ways to Protect Your Savings
Protection begins with separation and appropriate account choice. Keep emergency savings in an account that is liquid and separate from everyday checking to avoid accidental spending. Consider institutions and account types that offer deposit protection and easy access while minimizing fees. Small habits, like automating transfers and reviewing fees annually, help keep the balance intact and accessible when needed.
- Use a separate high-yield savings account for better returns than basic checking.
- Automate weekly or monthly transfers to make saving effortless.
- Avoid tying emergency funds to illiquid investments that penalize early withdrawals.
- Reassess your target after major life changes such as a move or job change.
These practical steps reduce friction and safeguard the core purpose of the fund: ready access in an emergency. Regular reviews ensure the account remains aligned with your goals.
Growing Savings Without Excess Risk
Once a baseline cushion is established, consider modest strategies to enhance returns while preserving liquidity. Short-term instruments like certificates with staggered maturities, money market accounts, or ultra-short bond funds can offer incremental yield without exposing the principal to large swings. Focus on predictable, low-cost options and avoid speculative moves that could undermine the fund’s reliability. Balancing yield with accessibility is essential for an emergency-focused portfolio.
Document your approach and keep it conservative: the priority is security, not maximum return. Periodically rebalance to maintain the intended risk profile.
Conclusion
Treat your emergency savings as a mission-critical component of financial health.
Protect it with separation, automation, and low-risk account choices.
Grow it conservatively so funds remain available when you need them most.

