Cash flow is the foundation of healthy personal finances and the difference between long-term goals and short-term stress. Understanding how money moves in and out of your accounts helps you prioritize spending, save effectively, and respond to unexpected expenses. This article outlines practical concepts and actions you can apply regardless of income level. The focus is on clarity and repeatable habits that create measurable improvement.
Understanding Cash Flow Basics
Cash flow means tracking all incoming money and every outgoing payment over a period, typically monthly. Positive cash flow occurs when inflows exceed outflows, enabling saving or investing; negative cash flow requires adjustments to avoid debt accumulation. Key factors include timing of paychecks, recurring bills, and discretionary spending, all of which influence liquidity. Recognizing seasonal or irregular income patterns is essential for accurate planning.
Regular monitoring reduces surprises and empowers better decisions. Simple visibility gives you leverage to reallocate funds toward priority goals without sacrificing financial security.
Practical Steps to Improve Cash Flow
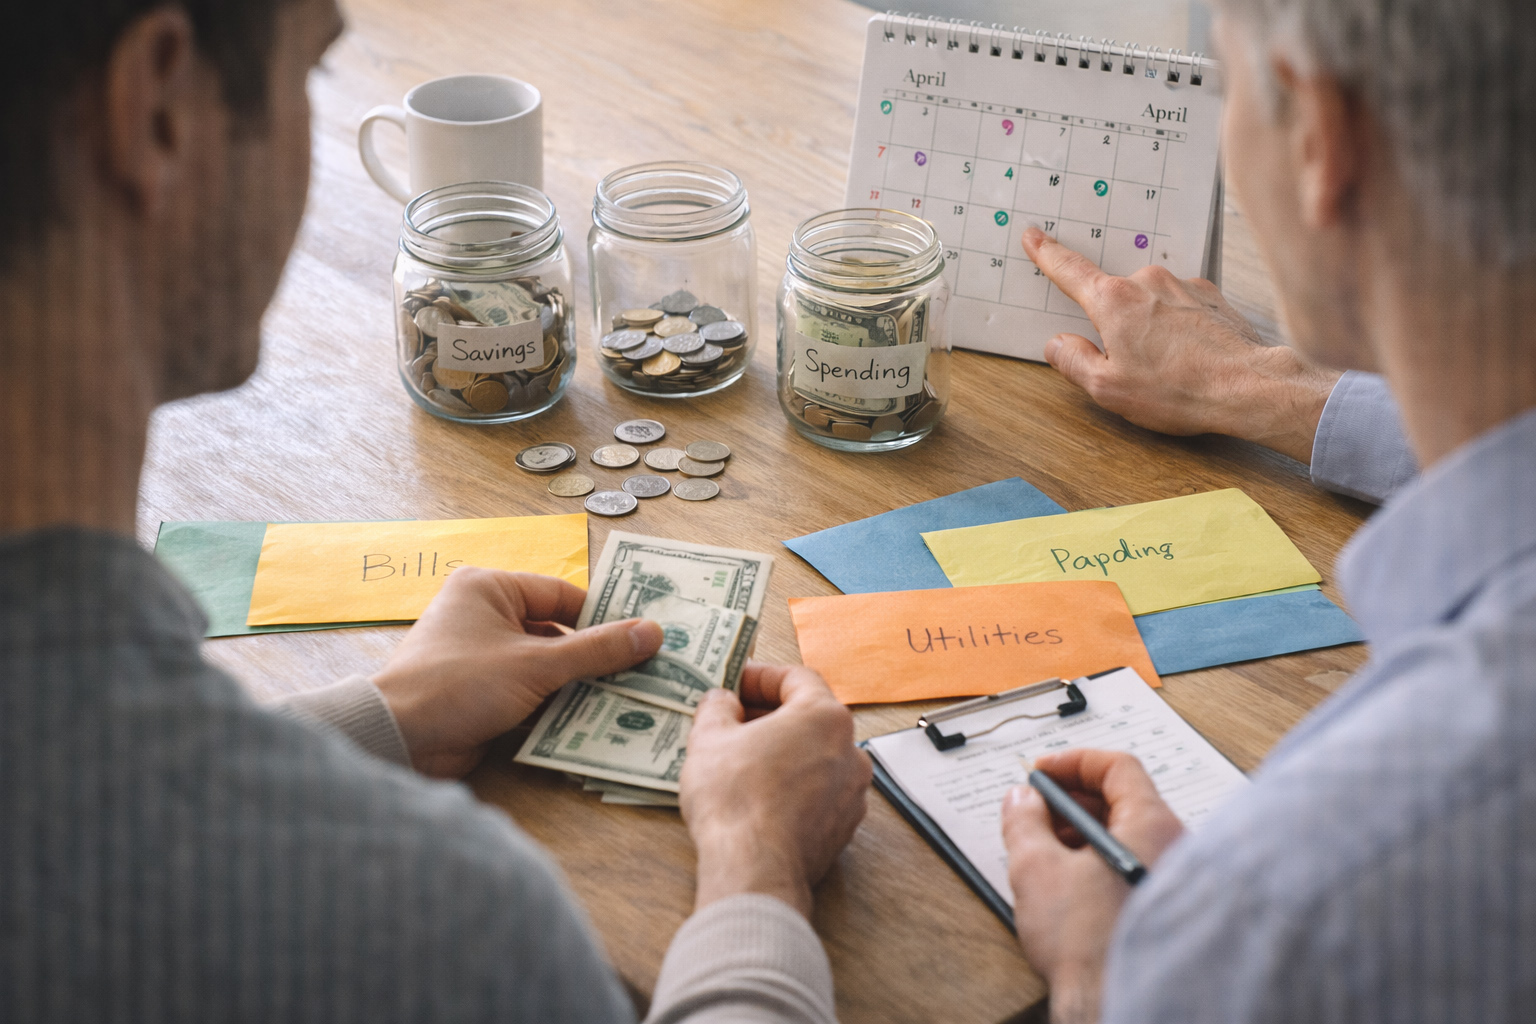
Start by creating a realistic, categorized budget that reflects current habits rather than ideal behavior. Prioritize essentials—housing, utilities, transportation, and food—before allocating money to wants or investments. Short-term goals like building a small emergency buffer will stabilize cash flow faster than distant objectives. Review subscriptions and recurring charges frequently to eliminate low-value outflows.
- Track daily expenses for 30 days to identify patterns.
- Automate transfers to a savings account on payday.
- Negotiate service providers or switch plans to reduce recurring bills.
- Create a 3-month plan to shift discretionary spending toward debt reduction or savings.
Implementing a few targeted changes can free up meaningful monthly cash and create momentum. Small, consistent adjustments compound into sustained improvement.
Tools and Habits to Maintain Momentum
Leverage simple tools like spreadsheets, budgeting apps, or calendar reminders to keep cash flow visible. Weekly check-ins that take 10–15 minutes are often enough to catch drifting habits before they become problems. Develop a habit of reviewing upcoming payments and reallocating funds when income timing changes. Periodic re-evaluation of your budget ensures it adapts to life events or shifting goals.
Combine automated systems with manual oversight for the best balance of convenience and control. Over time, these habits reduce stress and make growth decisions more intentional.
Conclusion
Consistent cash flow management turns routine decisions into reliable progress toward financial goals. Focus on visibility, small habit changes, and the right tools to sustain momentum. With steady practice, cash flow becomes an asset rather than a constraint.

