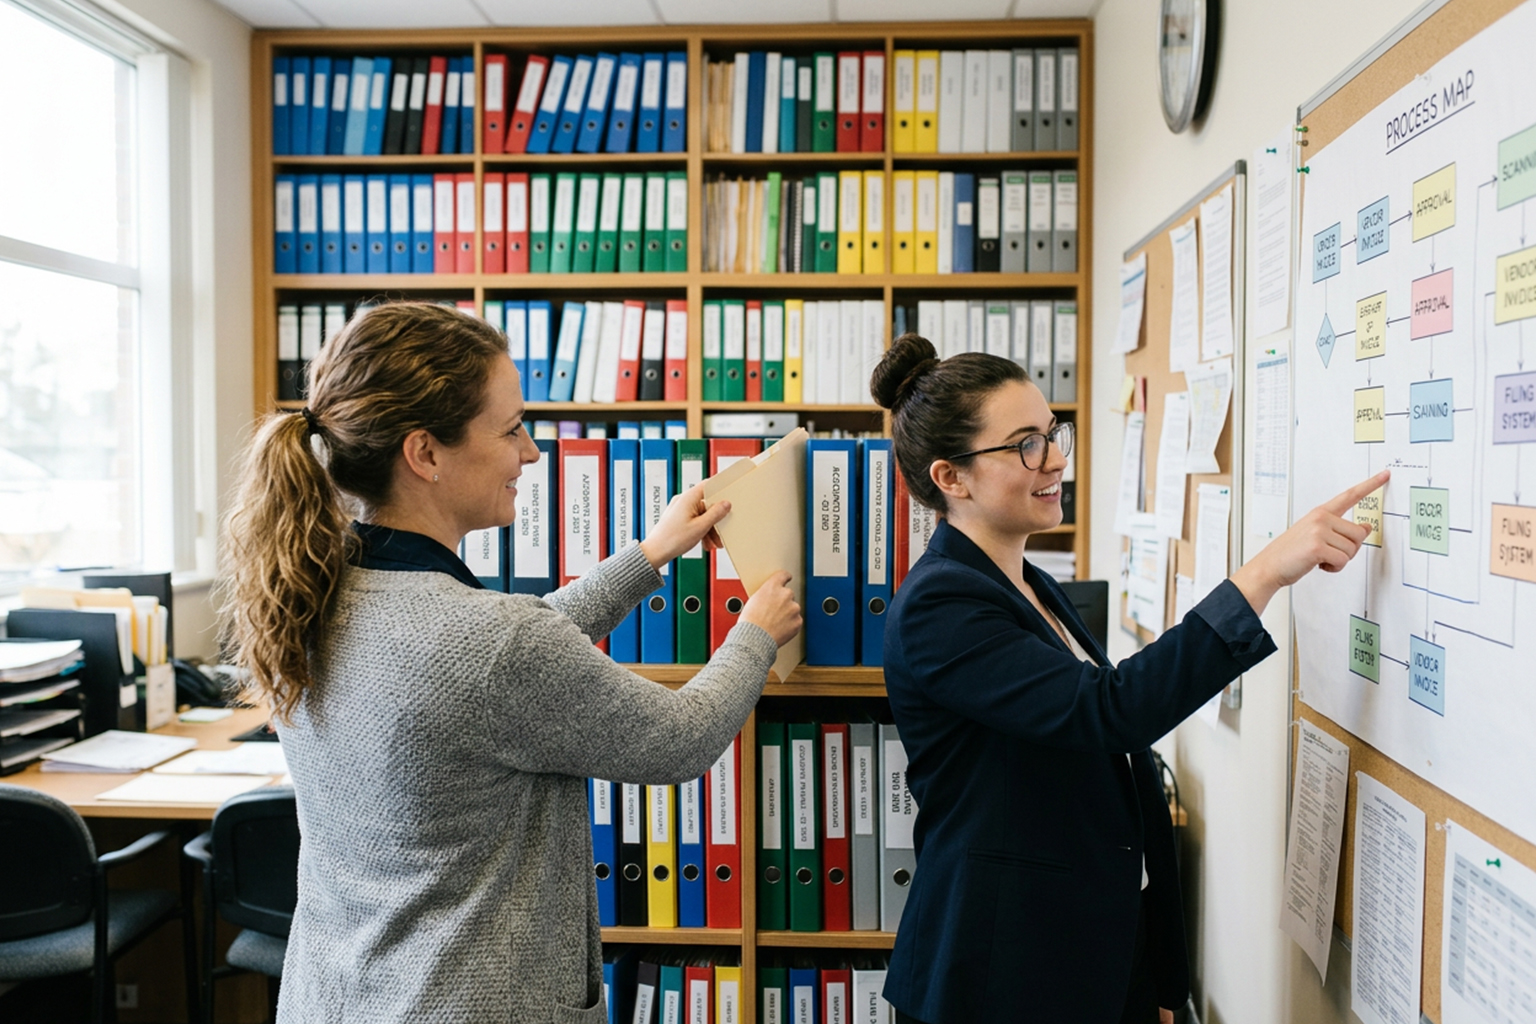
Financial teams spend too much time locating records and reconciling inconsistencies during month-end close. Organizing documents around business processes reduces friction and makes responsibilities clearer. A process-based filing model groups records by the workflow they support rather than by author or system. That shift simplifies access, speeds reporting, and lowers the risk of missing or duplicated files.
Adopting this approach does not require a wholesale systems replacement; it starts with principles and consistent execution. With modest governance and thoughtful metadata, teams can transform chaotic repositories into reliable sources for reporting. The sections below outline practical steps to design and sustain a process-first filing system.
Why process-based filing matters
Process-based filing aligns documents to how work is actually performed: accounts payable, revenue recognition, payroll, treasury, and so on. When files are organized by the steps in those processes, team members find what they need without guessing file names or asking colleagues. That clarity reduces time spent on searches and decreases interruptions during critical periods like closes and audits. It also makes handoffs between roles more predictable and auditable.
Shifting to this model surfaces gaps in controls and documentation because missing artifacts become obvious. Over time, the repository becomes both a workbench for daily operations and a defensible archive for compliance. Emphasizing process over person reduces single-point knowledge risk.
Designing folders, metadata, and naming
Begin by mapping core financial processes and the document types each requires, then create a consistent folder structure that mirrors those steps. Use simple, descriptive folder names and a short set of mandatory metadata fields—process, period, entity, and document type—to improve searchability. Combine naming conventions with metadata so that files remain meaningful even if moved between systems.
- Keep folder depth shallow to avoid buried files.
- Standardize date formats and version suffixes.
- Require a minimal metadata set during upload.
These design choices make automation and retention policies easier to apply, and they support quick, accurate retrieval during reporting and audit cycles.
Operational practices and governance
Assign process owners who maintain structure and enforce metadata rules, and provide templates for recurring document types to reduce variability. Train teams on the rationale behind the structure so adoption is consistent, and schedule periodic reviews to retire obsolete folders or update taxonomy. Integrate simple automated checks where possible to flag missing metadata or out-of-scope documents.
Regularly measuring search time, close duration, and audit findings helps demonstrate improvements and directs further refinements. Governance should be light but steady to avoid drift while enabling flexibility for unique scenarios.
Conclusion
Organizing financial records around business processes improves findability, reduces close time, and strengthens controls. Start small with core processes, enforce metadata, and assign owners to sustain the model. Over time, a process-based repository becomes a dependable foundation for faster, more accurate reporting.
