Financial reporting depends on timely, accurate records and predictable workflows. Adopting streamlined habits around document capture, organization, and review can shave days from month-end close cycles. Small changes to naming, metadata, and access controls compound across teams and reduce time spent searching for source documents. This article outlines practical habits to tighten record processes and improve reporting speed without major system overhauls.
Capture and centralize consistently
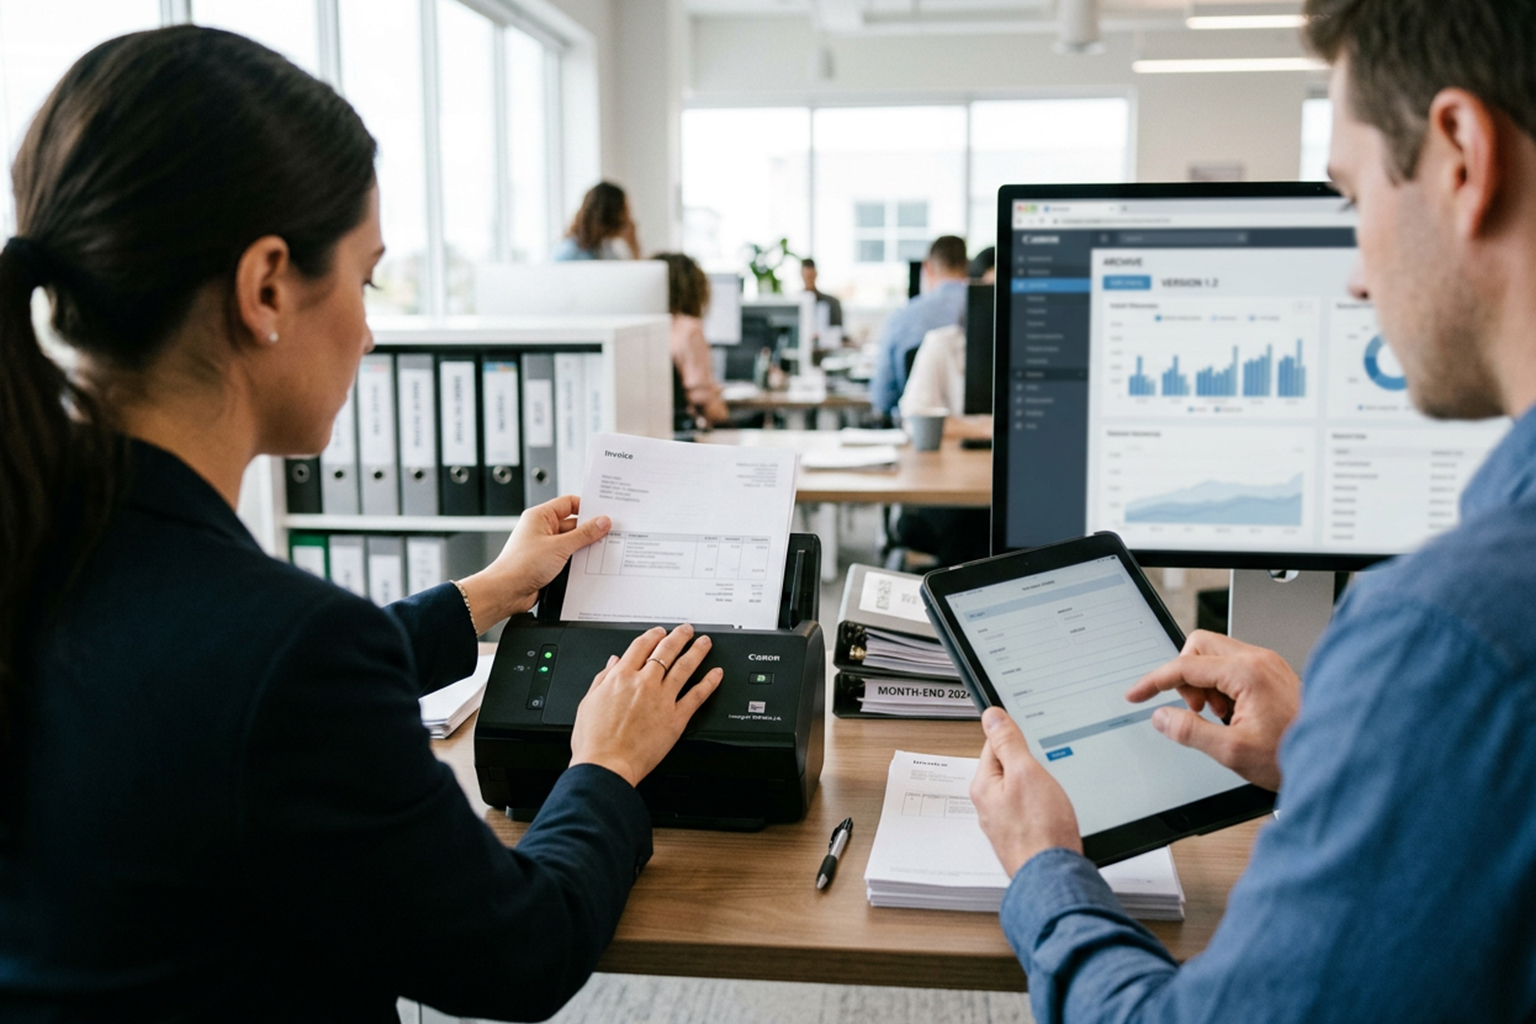
Emphasize capture at source, prefer digital ingestion and standard formats, and ensure receipts and invoices are scanned promptly with OCR to preserve searchable content. Use a single central repository or clearly synced folders to avoid version proliferation and duplicated effort that slows reconciliations. Enforce consistent naming templates so files are discoverable by date, vendor, and document type to reduce lookup time. Simple intake rules cut ambiguity when staff from multiple teams contribute records across departments.
- Require minimum metadata at upload, such as period and document type.
- Prefer PDF/A or other long-term formats for financial records.
- Automate OCR and basic field extraction where possible.
Regularly audit new entries to ensure capture rules are followed and correct any deviations quickly. Immediate feedback helps maintain discipline and keeps the repository clean for month-end activities.
Metadata, taxonomy, and searchability
Add structured metadata fields for period, entity, and category so filtering yields precise results and reduces manual sorting. A lightweight taxonomy mapped to reporting needs ensures teams can locate statements, contracts, and reconciliations without lengthy queries. Metadata also supports automated workflows such as routing invoices to approvers or flagging documents for audit review. Prioritize a small set of high-value fields over exhaustive tagging to minimize user burden and improve compliance.
Train users on the minimal metadata set and integrate sensible defaults where possible to speed capture. Good taxonomy reduces repeat clarification requests and accelerates reporting tasks across stakeholders.
Automate routine tasks and set review cadences
Leverage automation to extract key values, populate metadata, and flag missing signatures or approvals so exceptions surface early. Automated validation rules can highlight mismatched totals, missing back-up, or incomplete reconciliations before the close window. Combine automation with a clear review cadence so reconciliations and adjustments are addressed in predictable windows rather than at the last minute. A short, regular review rhythm prevents scramble and keeps close processes steady across departments.
Define owners for each recurring review and measure cycle times to find bottlenecks and inefficiencies. Continuous small improvements compound into measurable reductions in reporting time.
Governance, permissions, and audit readiness
Establish clear permissions and role-based access so only authorized users can modify sensitive financial records while reviewers retain appropriate read rights for transparency. Maintain version control and an immutable audit trail to trace changes, support internal review, and satisfy external audit inquiries. Apply retention schedules tied to regulatory and business needs to reduce clutter and ensure relevant documents remain discoverable when needed. Document approval paths for adjustments and edits to limit ad-hoc changes during critical close periods.
Communicate governance rules and test access scenarios periodically to identify and remediate gaps before they affect reporting. Well-applied controls reduce rework and increase confidence in reported numbers across finance and operations.
Conclusion
By standardizing capture, metadata, and automation, finance teams can shrink reporting cycles without large investments. Consistent habits and defined reviews create predictable, auditable workflows that support faster decisions. Start with one small rule and expand incrementally to sustain momentum and measurable gains.

